Conflicting Dashboard Metrics and Board Meeting Credibility
Conflicting metrics destroy board credibility when definitions silently drift across systems.
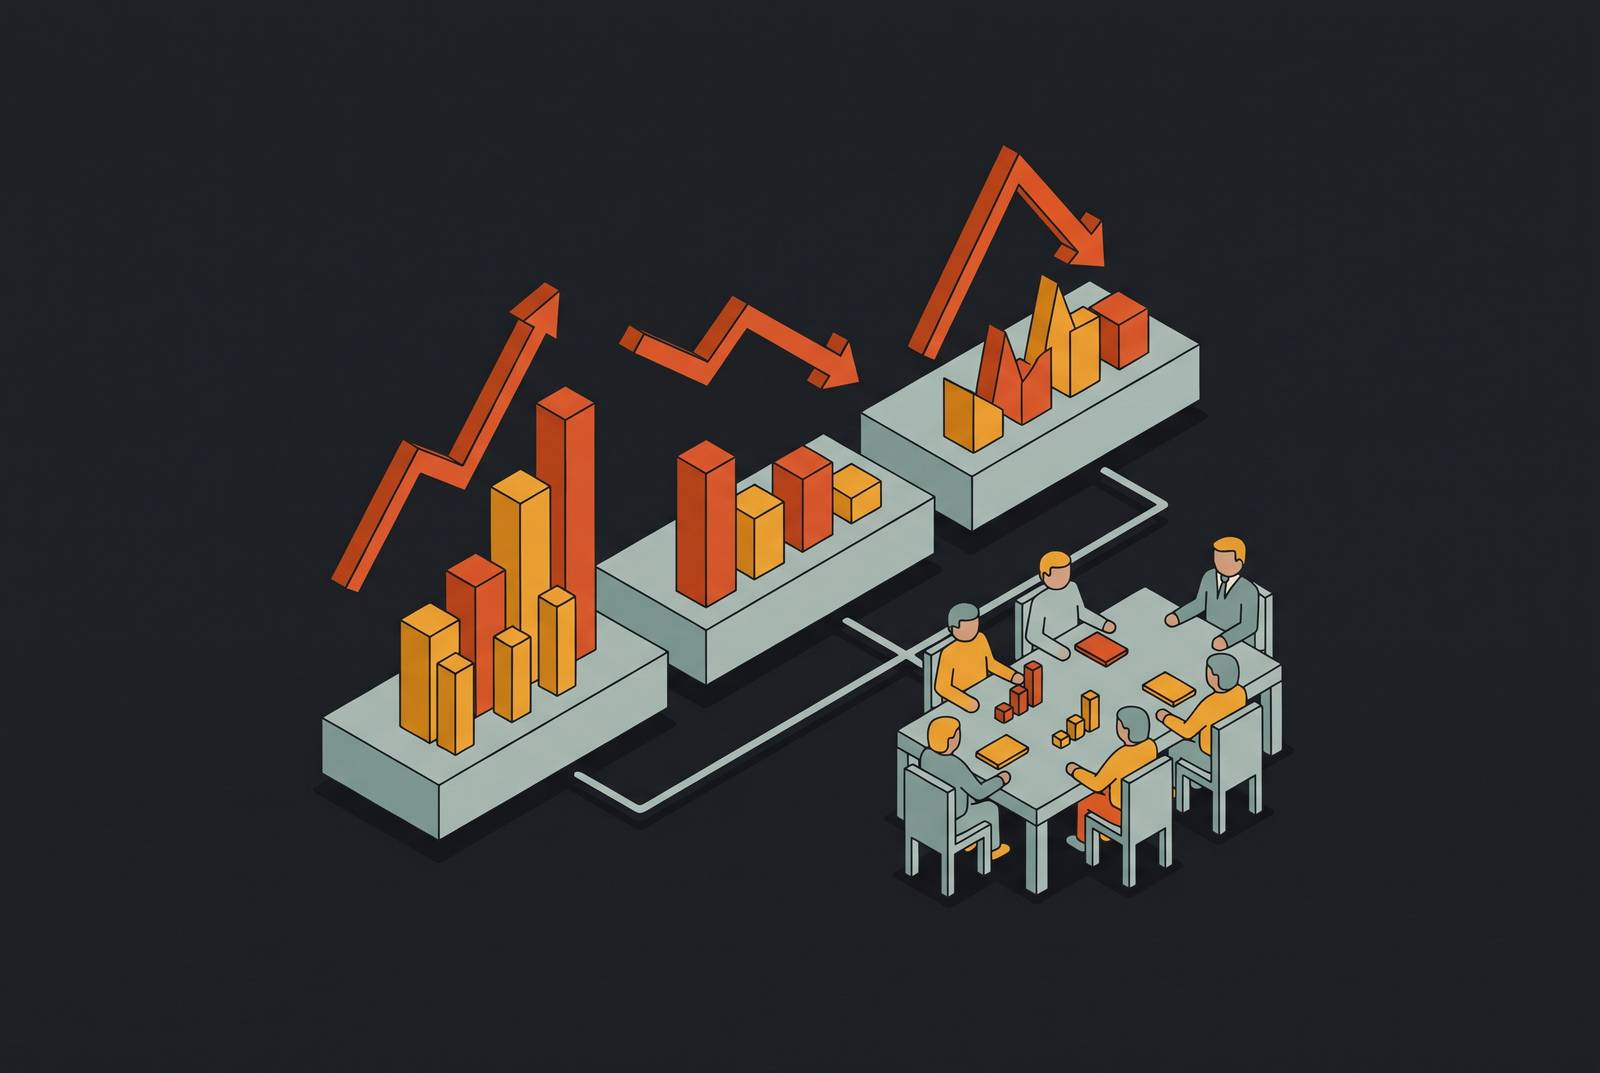
When dashboard metrics disagree, the board loses trust because the company cannot give a consistent account of how it is doing. The cause is usually not poor visualization or missing data, but definitions that differ across systems and reports. To win back trust, the company needs a single governed source of truth, with meanings people agree on, named owners, and calculations people can trace, for both board dashboards and AI agents.
Why boardroom credibility breaks over numbers that were never defined the same way twice
Each number has a defensible calculation behind it. None agrees with the others. The immediate temptation is to blame the dashboard, the tool, or the analyst assembling the deck, but the disagreement begins before the numbers reach the screen.
The public consequence arrives when a director asks why churn in the current deck differs from last quarter’s PDF. “We changed the definition” shifts the discussion from business performance to whether the comparison is valid. Bad results can be explained against a stable baseline. When the definition changes, management loses that baseline and must explain what the number means before it can discuss what caused it. Revenue booked and revenue recognized can both be legitimate measures, but neither can silently substitute for the other.
How metric definitions drift by default when systems are built for different purposes
Salesforce supports a sales process, Stripe reflects billing events, and the finance model serves control and auditability. Their purposes differ before reporting even begins. The CRM may count a customer on contract signature while finance counts on invoice. Billing can reflect a downgrade immediately while the board deck still applies spreadsheet logic from two quarters ago. ARR and churn then depend on which system’s rules the report inherits.
A calendar month differs from a rolling month, just as booking date differs from effective cancellation date. Faster updates will not reconcile those choices. A dashboard refreshed at 06:00 can also disagree correctly with one refreshed at 14:00, yet without a visible “data as at” stamp, readers see an apparent error. Hidden exclusions, regional slicers, and row-level security rules can also make numbers differ in ways that look like arithmetic mistakes because the report does not show what it covers.
How report sprawl turns a local definitions problem into an organization-wide trust problem
As dashboards become easier to build, local interpretations gain more places to circulate. Sales operations creates a pipeline view, finance builds a margin report, and operations assembles a utilization dashboard. Each serves a reasonable local purpose on its own. Together, they create more occasions for leadership to stop and ask which version is authoritative.
Copies make the problem harder to contain. Someone downloads a certified report, adds two columns, and circulates the modified file from a shared drive for a year. That file becomes a competing source without an owner. Analysts spend more time explaining discrepancies, while leaders fall back on spreadsheet reconciliation and gut instinct. The board pack concentrates this accumulated inconsistency into one document, exposing outside decision-makers to disagreements that individual teams could previously overlook.
What investors and board members are actually reading for when they see conflicting numbers
Directors need to distinguish a change in performance from a change in measurement. NRR cannot support that distinction when cancellations, contractions, and non-renewals are handled differently from quarter to quarter. When churn looks manageable in one view and alarming in another, directors have no sound basis for comparison. Management must defend the population, period, and exclusions before it can explain the commercial result.
HelpWithMetrics names pipeline coverage below target and NRR below 100% as red flags for investors. Those measures need definitions that hold up to pressure-testing, even when the figures look sound on their own. Using a different file for sales and marketing spend can also change CAC payback while the business itself stays the same. Consistency makes the trend available for scrutiny. Three or four quarters measured on the same basis allow directors to ask sharper questions, while an unstable baseline forces each meeting to begin by reconstructing the supporting data.
Why better charts and faster refreshes don't fix the underlying disagreement
KDG’s dashboard trust analysis identifies definitions as a prerequisite for dashboard trust, ahead of design. A clear chart makes the calculation behind it easier to see, but cannot settle whether it measures booked or recognized revenue. Better presentation can make the contradiction more conspicuous. Buying another BI platform leaves the same unresolved choice underneath a different interface, because tools can enforce decisions but cannot make the business agreement themselves.
Two dashboards measuring different things will still disagree when both update in real time. Automation can likewise deliver an unresolved definition more efficiently. The strongest attraction of a tooling fix is that it is tractable, while agreement between finance and sales can be slow and politically difficult. A dashboard may ship in a week, but the trust layer requires agreement on source mappings, counting rules, and exceptions that a quick build does not supply.
What a governed metric layer actually looks like and how it resolves conflicts at the source
A governed metric layer sets out what each measure means before a downstream report uses it. For gross margin, that means finance and operations agree on one meaning and apply it across their reports. The agreement must be explicit and inspectable. Mio’s reconciliation guide describes a metric contract covering what the business needs to know, unit, population, time, definition, exclusions, and source and owner, kept beside the query link. A cut-off rule and effective date establish which version applies to a particular result.
Certification separates authoritative reporting from useful experimentation without banning either. A small certified core is kept under tight control, while a clearly labeled sandbox gives people room to explore. Neither unrestricted publishing nor a central reporting queue fits the need on its own. Every metric on the CEO dashboard should reconcile to one source, with ARR from billing, cash from the bank, and product usage from the analytics layer. That arrangement stops separate departmental versions from becoming interchangeable board figures.
Change control preserves the value of the initial agreement. When a definition changes, a decision log records the break rather than rewriting history as though the new rule had always applied. Readers can then tell whether the business changed or the way it was measured changed. The technical layer makes agreed rules reusable, but ownership remains organizational. Software cannot resolve a dispute about how revenue should count when finance and sales have not agreed on its business meaning.
Which metrics a Series A board dashboard should govern first, and in what order
For a founder or early operator, the practical sequence is to govern the measures the next board meeting will challenge, rather than every metric the company might eventually track. Before product-market fit, deprioritize LTV, CAC, payback period, and burn multiple. The inputs are not yet stable enough. Optimizing those measures prematurely can push a team toward scaling something that does not work, even when the calculations themselves appear precise.
At early traction, certify MRR components, logo churn, gross revenue retention, and runway. These establish whether the customer base is stable and whether the business can reach its next milestone. Add CAC by channel once acquisition becomes repeatable. Adding it takes agreed meanings for marketing spend and sales spend that stay the same over time, even when expense data is already at hand. The sequence keeps the governed core tied to decisions the business is ready to make.
Once there is enough quarterly history, make the five-quarter finance view the certified tier for the board. It includes ARR growth rate, NRR, gross and net churn, burn, runway, CAC payback, and pipeline coverage. Throughout this progression, keep a written definition and a single source of truth for every metric in use, agreed across the departments that depend on it. Even when departments draw from the same system, they can still apply different rules.
How AI agents in the data stack make ungoverned metric definitions a security and accuracy problem, not just a reporting one
An AI agent querying business data inherits the same ambiguity as an uncontrolled report. If revenue has several meanings, different phrasings can produce different answers to what the user considers the same question. Conversational analytics instead exposes naming gaps that a human reader might have reconciled manually. Teams deploying it therefore need governance before rollout, rather than treating governance as a later reporting improvement.
Direct production access adds performance and security risks to the risk of inaccurate answers. A poorly scoped financial query may use data the agent was never meant to access. The recommended pattern gives agents access to governed, pre-modeled datasets through a controlled interface that keeps the raw production database out of reach. A fraud detection agent can then receive transaction amounts and timestamps without payment card numbers or customer names, because governance filters the return at query time.
MCP, the Model Context Protocol, standardizes how agents call tools and access resources. It is an interface. The data platform beneath it still needs identity, semantic grounding, query performance, lineage, cost controls, and auditability. A standard connection cannot settle what revenue means or which records an agent is allowed to use.
How Supabase teams in particular are exposed to the definitions problem from day one
For teams building on Supabase, database creation and population can outpace the reporting layer from the start. An unobserved Postgres instance leaves the team without a query performance baseline, an audit trail, or a canonical account of which tables power which metrics. Reporting begins without those points of reference. By board preparation time, the founder may be reconciling Stripe webhooks against Postgres event tables and a spreadsheet. A schema modified by an agent adds another complication to that reconciliation.
Supabase provides observability tooling, including log drains on paid plans that ship to downstream destinations. Those logs supply raw material for monitoring. They do not establish a shared definition of ARR, churn, or an active customer. Observability describes what happened in the system, while a governed metric layer establishes how those events count toward a business measure.
A governed data layer built for Supabase teams that serves both the board dashboard and the AI agents in the stack
Pre-modeled metrics in governed Parquet datasets queryable through DuckDB give agents context without access to the production database. That separation removes the performance and security exposure associated with raw agent queries against live transactional tables. A single MCP server can expose the governed layer to AI workflows, so an agent answering a revenue or churn question uses the certified metric behind the board dashboard.
Delivery cadence can reinforce that common definition. Metrics should be calculated ahead of time and pushed to the inbox, Slack, and the board pack rather than retrieved only when someone remembers to check. Every destination receives the same certified measure. Early-stage teams can hire an analyst, build with BI tools, or use a done-for-you governed layer, depending on their time and capacity to own the governance work. The standard for any path is that the CEO can defend a number on a slide by tracing it to an agreed definition, with its meaning settled before the meeting.